Aug 26, 2026
Buying Property in Goa from an NRI, OCI, PIO or Foreign National – TDS/Power of Attorney/TAN
Buying property from an NRI, OCI or PIO in Goa involves different TDS rules and documentation requirements. Understand TDS, Power of Attorney, TAN requirements and the key steps to follow before completing the property transaction.
Goa has a large number of property owners who have settled abroad. Some are Non-Resident Indians (NRIs), while others have acquired foreign citizenship and may hold OCI or PIO status.
Buying a property from such a seller is perfectly possible, but the tax and documentation requirements can be very different from a normal property transaction between two resident Indians.
Here are some important points every buyer should know.
1. First, check the seller's residential status
Citizenship and tax residency are not the same thing.
An Indian citizen living abroad may be an NRI for Indian income-tax purposes. A foreign citizen may be an OCI, but the important question for TDS is whether the seller is resident or non-resident under Indian tax law.
This should be established before the sale agreement is finalised.
2. TDS when buying from a resident Indian
When buying property from a resident Indian, the familiar rule is:
If the property value is ₹50 lakh or more, the buyer generally deducts 1% TDS from the resident Indian Seller.
For a transaction below the applicable ₹50 lakh threshold, this particular TDS provision generally does not apply.
This is the rule under the provisions applicable to a resident seller.
3. Buying property from an NRI is different
If the seller is non-resident for Indian tax purposes, the ₹50 lakh rule does not apply.
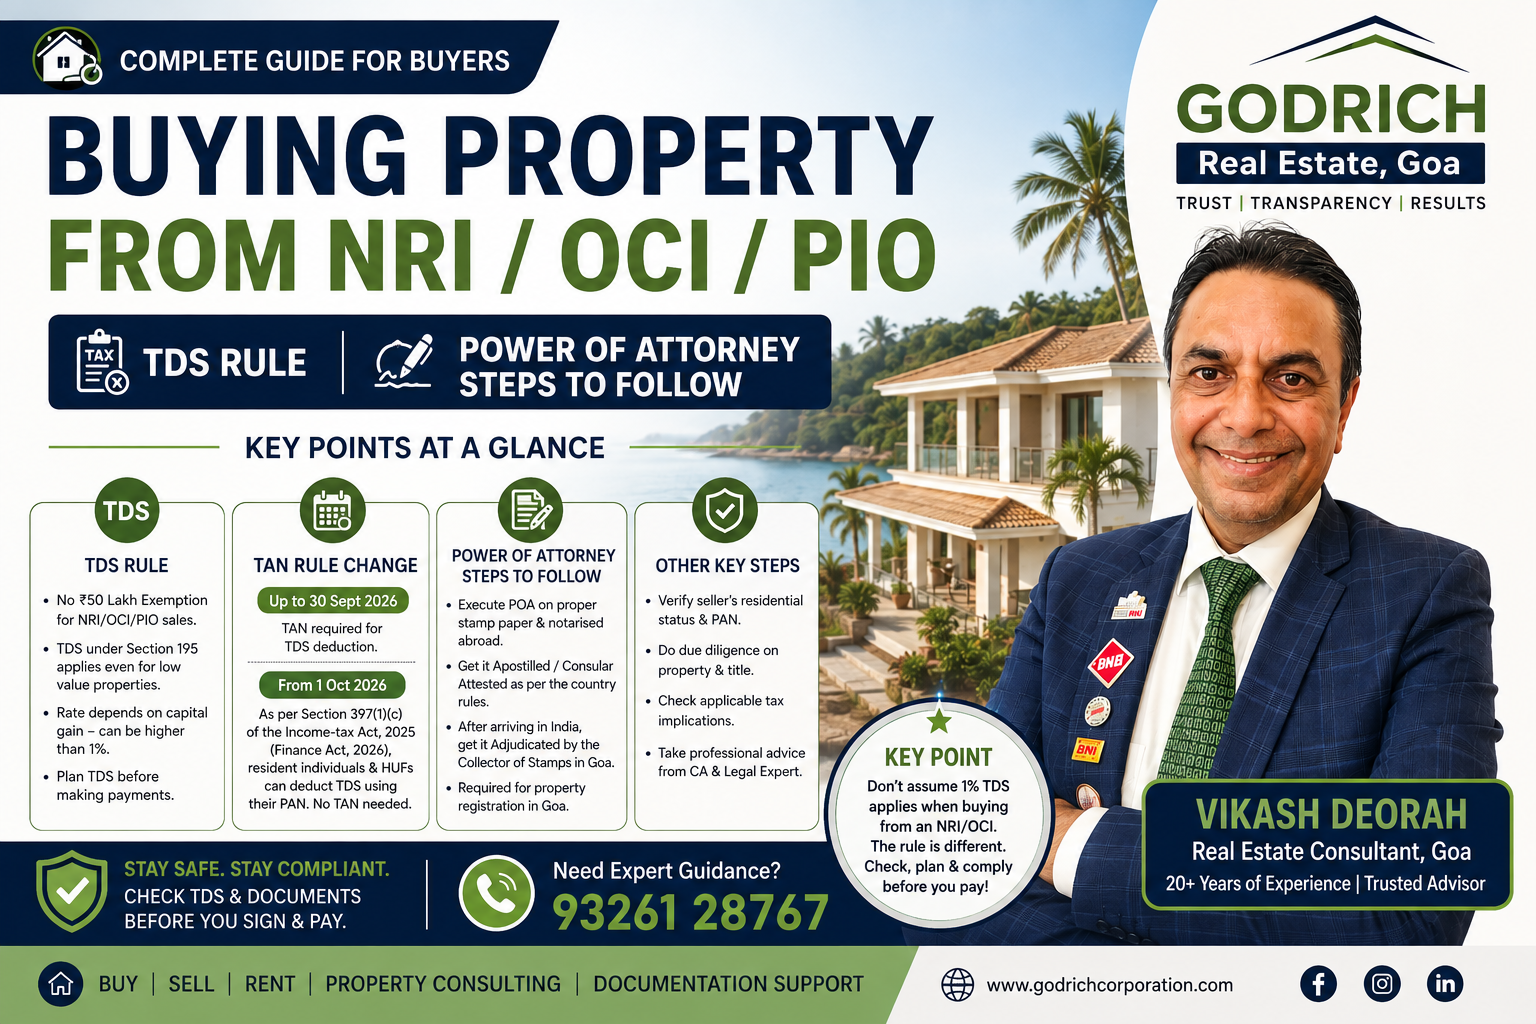
TDS is governed by Section 393(2) of the Income-tax Act, 2025 (corresponding to the earlier Section 195).
There is no ₹50 lakh exemption or any amount threshold like the one applicable to resident sellers.
In simple terms:
Even if the property is worth less than ₹50 lakh, TDS may still be applicable when buying from a non-resident.
The exact TDS depends on the nature of the income and the applicable tax provisions. For a long-term capital gain on immovable property, the current base rate is generally 12.5%, while short-term gains can be taxed differently. Applicable surcharge and cess may also apply.
Therefore, never assume that the TDS will be only 1% when the seller is an NRI or other non-resident.
4. Why this is important for the buyer
Suppose you are buying a Goa property from an NRI.
You cannot simply deduct 1% TDS because that is the rate you normally hear about for property transactions.
The NRI transaction has a separate TDS procedure, and the amount to be deducted can be substantially higher.
If the seller believes that the actual tax payable is lower, they can explore obtaining a lower or nil TDS certificate from the Income Tax Department.
Therefore, the TDS calculation should be completed before making substantial payments or finalising the sale agreement.
It is strongly advisable for both buyer and seller to have the transaction checked by a Chartered Accountant familiar with NRI property transactions.
5. Important change from 1 October 2026 – TAN will no longer be required for eligible buyers
There is an important change from 1 October 2026.
Under Section 397(1)(c) of the Income-tax Act, 2025, as amended by the Finance Act, 2026, a resident individual or HUF buying immovable property from a non-resident will no longer be required to obtain a separate TAN for deducting TDS under Section 393(2).
Instead, the buyer will be able to report the deduction using the buyer's PAN.
Until 30 September 2026
For an eligible resident buyer purchasing property from a non-resident:
TAN is required.
From 1 October 2026
For a resident individual or HUF:
No separate TAN is required; PAN-based reporting will apply.
This change is specifically designed to reduce the compliance burden on individuals who may otherwise have to obtain a TAN for a single property transaction.
The official Income Tax Department portal is:
Income Tax Department – e-Filing Portal
6. Power of Attorney – be very careful
A common situation in Goa is that the NRI or foreign-based owner does not travel to India and gives a Power of Attorney (POA) to a relative or representative in Goa.
The POA should not simply be typed, signed abroad and couriered to India.
The document has to be properly executed and authenticated according to the applicable rules of the country where it is signed.
Goa's Registration Department specifically states that a Power of Attorney executed outside India has to be adjudicated before the Collector of Stamps after it reaches India, within the prescribed period.
7. Apostille and Consulate – check the country before execution
If the POA is executed abroad, the authentication procedure depends on the country in which it is executed.
For countries covered by the Hague Apostille Convention, an apostille is generally used for international document authentication. The Ministry of External Affairs explains the apostille process and its purpose.
However, Goa's published registration guidance also refers to authentication by the Indian Embassy or Consulate for foreign Power of Attorney documents.
Therefore, before the NRI signs the POA abroad, confirm the exact authentication requirement with the relevant Indian Embassy/Consulate and the concerned Goa registration authority.
Do not assume that a generic POA or notarisation will automatically be accepted.
8. Adjudication in Goa
Once the original POA reaches Goa, it must be taken through the required stamp adjudication process before the Collector /dy. Collector of that area.
The Goa Registration Department states that a POA executed outside India should be adjudicated after its receipt in India within three months.
The appropriate authority and jurisdiction should be confirmed according to the location of the property and the registration office handling the transaction.
At the moment a Rs 500 special Adhesive stamp has to be affixed and signed by the competent Authority.
The orignal Adjucated power of Attorney has to be produced before the Registrar when the Sale Deed is executed
9. The simple checklist for a buyer
If you are buying a property in Goa from an NRI, OCI holder or other non-resident, check these points before signing the final agreement:
Confirm the seller's Indian tax residential status.
Verify the seller's PAN and identity documents.
Confirm the applicable TDS under Section 393(2).
Do not assume the ₹50 lakh/1% resident-seller rule applies.
If the transaction is before 1 October 2026, check the TAN requirement.
From 1 October 2026, check whether the buyer qualifies for the PAN-based facility under Section 397(1)(c).
If a POA is being used, ensure it is correctly executed and authenticated abroad.
Complete the required adjudication/stamping of the foreign POA in Goa.
Have the entire transaction reviewed by a CA and property lawyer before making major payments.
Final Takeaway
Buying a property from an NRI or non-resident is not difficult, but it is different from buying from a resident Indian.
The two areas that require the most attention are:
TDS: The ₹50 lakh threshold and 1% rule applicable to resident sellers only should not be blindly applied to an NRI/non-resident seller.
Power of Attorney: A POA executed abroad needs to follow the appropriate authentication and Goa adjudication requirements before it can safely be relied upon for registration.
A little additional due diligence before the transaction can save a buyer from significant tax, documentation and registration problems later.
Disclaimer
This article is intended only for general information and awareness. It should not be treated as legal, tax, financial or professional advice. TDS rates, tax laws, stamp duties, authentication requirements and government procedures may change from time to time. The exact tax treatment and documentation requirements depend on the facts of each transaction. Buyers and sellers should consult a qualified Chartered Accountant, tax professional and property lawyer before entering into or registering any property transaction.
*Information regarding the 1 October 2026 TAN change is based on the Income-tax Act, 2025 as amended by the Finance Act, 2026, including Section 397(1)(c) and Section 393(2). *